Learn · Guide
Your losses lower your tax. They don't lower your AGI.
The most expensive sentence in gambling tax isn't about the tax at all. It's this: winnings go into adjusted gross income before a single dollar of losses comes off.
The most expensive sentence in gambling tax isn't about the tax at all. It's this: winnings go into adjusted gross income before a single dollar of losses comes off.
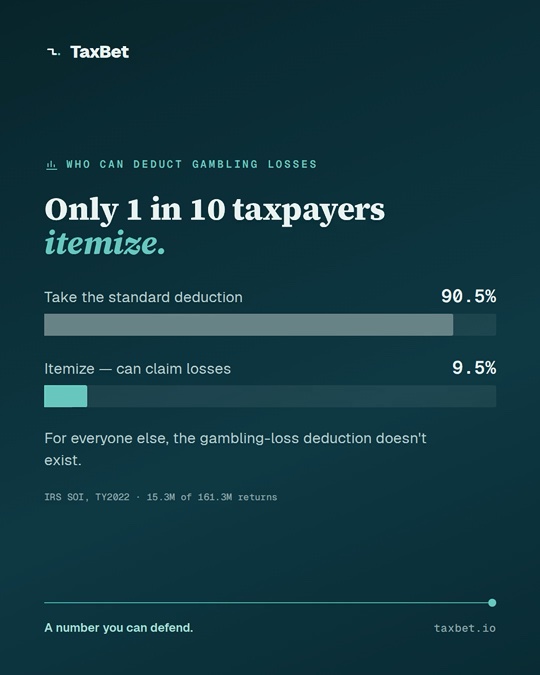
Session-method winnings are income — they land on Schedule 1 and raise your AGI. Losses deduct on Schedule A: below the AGI line, only if you itemize, and (from 2026) only up to 90% of losses. So even a break-even year pushes your AGI up by your full winning-session total. If you take the standard deduction, the losses never come off at all.
Illustrative — tax year 2026. Your own figures come from your upload.
AGI (and its cousin MAGI) is the number a long list of credits, deductions, and phase-outs read from:
Whether any of them applies to you depends on your full income picture, which TaxBet doesn't see — the point is that the winnings figure is what they key off, so getting it right is the only way to see a cliff coming. A break-even year at the casino can cost more in phased-out credits than in gambling tax itself.
You can't change how AGI works. The reported winnings figure can affect AGI. A documented session-based workpaper may provide a different figure for taxpayer and tax-professional review, depending on the facts, records, and applicable treatment — and that difference, documented, is the whole game.